
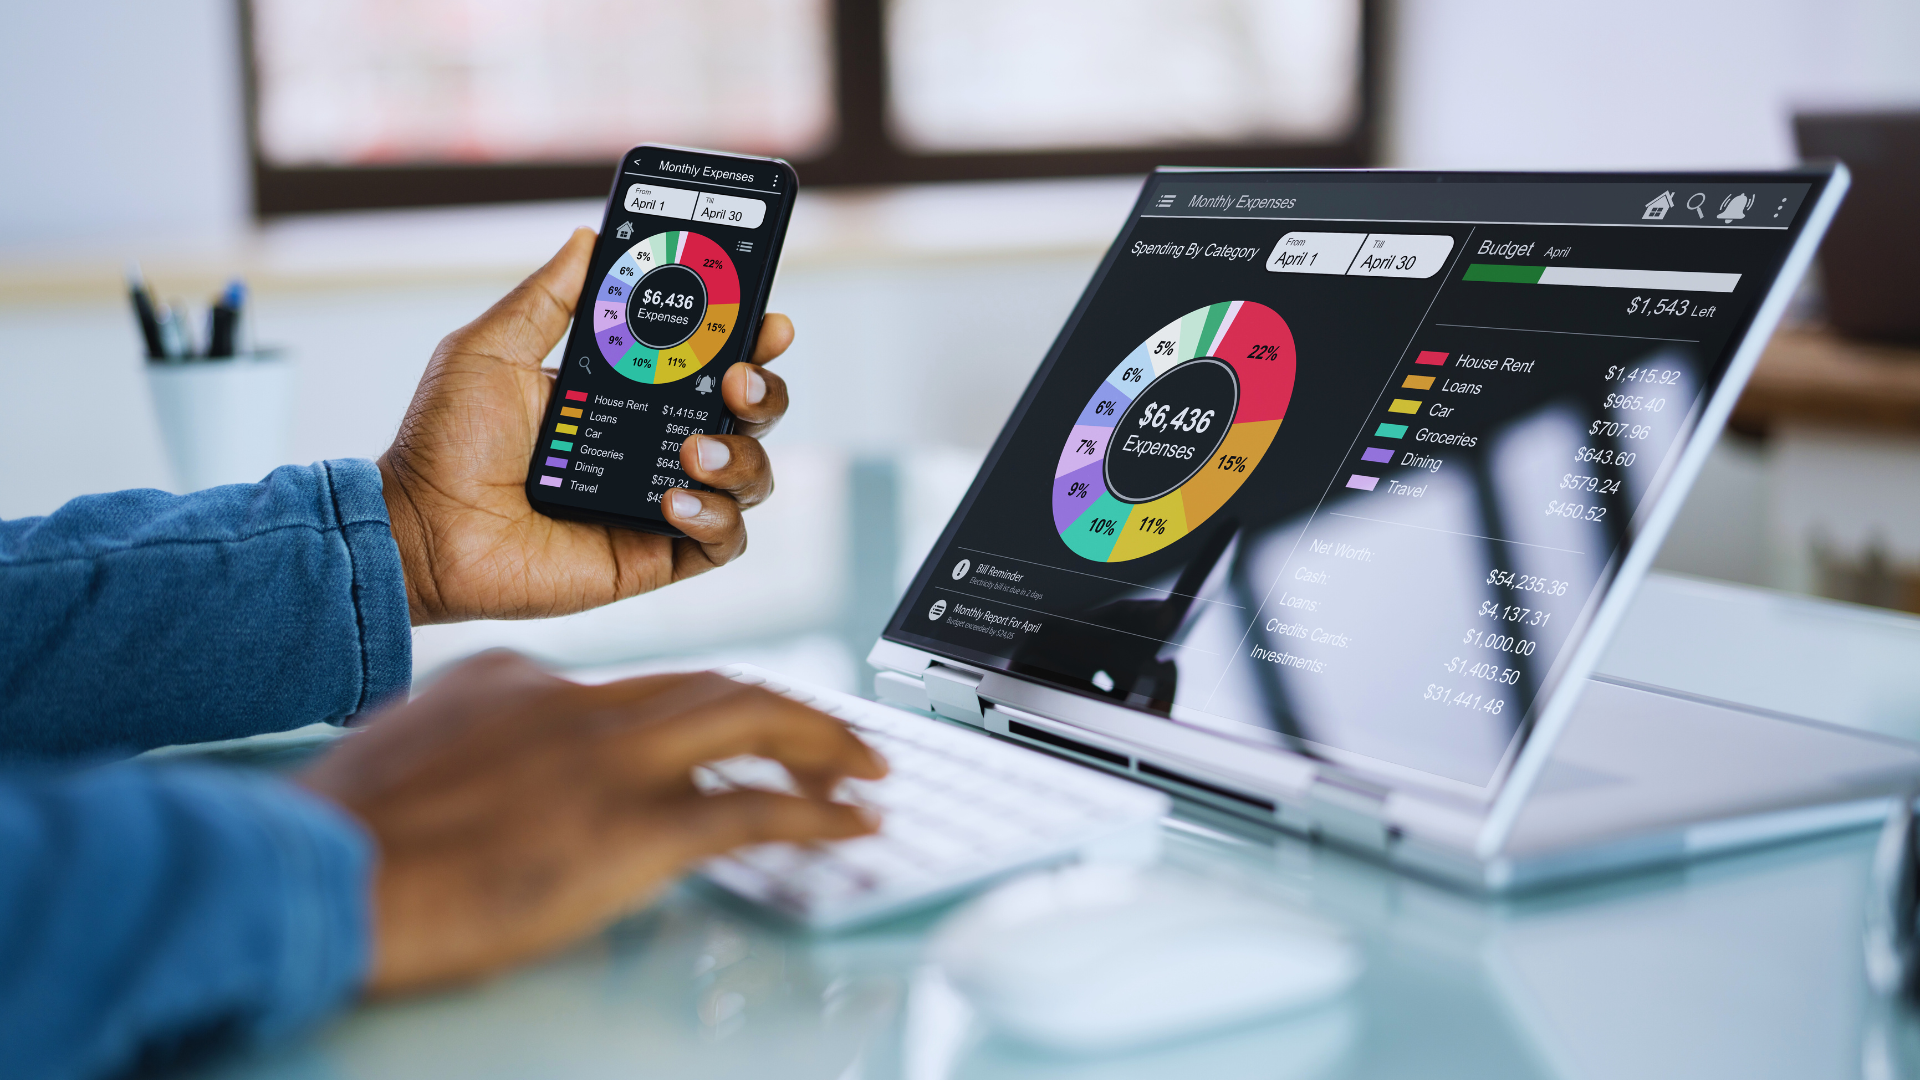
Automating savings can significantly simplify personal finance management. By setting up automatic transfers to savings accounts, an individual can make consistent progress toward their savings goals without requiring constant attention. This automatic approach builds a habit of saving that contributes to long-term financial well-being.
Establishing automation reduces the temptation to spend money that should be saved. The convenience of transferring a fixed amount regularly helps individuals stick to their plans. Over time, this not only cultivates discipline but also leads to peace of mind, knowing that savings are accumulating steadily.
Financial automation tools are widely available, making it easier for anyone to take control of their savings journey. With just a few simple steps, a person can create a system that works for them, aligning their savings strategy with their lifestyle and goals.
Understanding the Basics of Savings Automation
Savings automation simplifies the process of setting aside money regularly. This section explores automated saving, its benefits, and the various types of accounts suited for these transactions.
What Is Automated Saving?
Automated saving involves setting up regular transfers from a checking account to a savings account without requiring manual intervention. It uses technology, like banking apps or online banking systems, to allocate funds automatically at specified intervals, such as weekly or monthly.
This process ensures consistent savings habits and helps individuals reach financial goals, whether it’s for emergencies, vacations, or larger investments. Once the system is set up, it requires minimal effort, helping to build wealth over time.
Benefits of Automatic Transfers
Automatic transfers provide several advantages. Firstly, they can help eliminate the temptation to spend surplus cash. When funds are automatically moved to savings, the remaining balance in the checking account is what can be spent.
Additionally, automating savings creates structure. Individuals can align transfers with payday schedules, making it easier to save consistently. It can also lead to higher savings rates, as regular deposits help grow interest in savings accounts.
It is a proactive approach to personal finance management and aids in achieving specific savings targets more effectively.
Types of Accounts for Automated Savings
Several account types are suitable for automated savings. A savings account is the most common choice, as it typically offers interest on the balance while allowing for easy access to funds.
Another option is a high-yield savings account, which provides a higher interest rate than standard accounts, maximizing earnings on saved funds. For specific goals, individuals may consider certificates of deposit (CDs), which usually offer better rates for funds locked away for a set period.
Lastly, some people utilize investment accounts for long-term savings goals, combining automation with potential growth in a different market. Each account type has its uniqueness and benefits, catering to different financial strategies.
Setting Up Your Automatic Savings Plan
Establishing an automatic savings plan involves selecting a financial institution, defining specific savings goals, and arranging direct deposits or transfers from your paycheck. These steps help ensure a disciplined approach to saving.
Choosing the Right Financial Institution
Selecting a financial institution is the first step in setting up an automatic savings plan. Options include banks and credit unions. Each has its own benefits, such as interest rates, fees, and accessibility.
When evaluating institutions, consider these factors:
- Interest Rates: Look for competitive rates that will maximize savings.
- Fees: Be aware of any monthly maintenance fees that could eat into savings.
- Accessibility: Choose an institution that offers easy online banking and mobile app access for convenience.
After comparing options, open an account that aligns with your financial needs.
Defining Your Savings Goals
Defining clear savings goals is essential for effective saving. Goals should be specific, measurable, achievable, relevant, and time-bound (SMART). This clarity provides motivation and a sense of direction.
Consider the following examples of savings goals:
- Emergency Fund: Save three to six months’ worth of expenses for unexpected events.
- Vacation Savings: Set aside money for future travel plans, specifying an amount and timeline.
- Large Purchases: Plan for significant expenses, like a home or car, by determining a budget and time frame.
Writing down these goals can enhance commitment and facilitate progress tracking.
How to Set Up Direct Deposit and Transfers
Setting up direct deposit or automated transfers from a paycheck is crucial for an automatic savings plan. It ensures consistent contributions to savings without manual intervention.
To begin, speak with your employer about direct deposit options. They may require details of the chosen financial institution. Once the deposit is established, designate a percentage or specific amount to be transferred to the savings account.
For those preferring manual transfers, schedule automatic transfers at regular intervals, typically right after payday. This can be done via online banking, allowing for easy adjustments as income or expenses change. Automating this process helps reinforce savings discipline.
Maximizing Your Savings Automation
Automating savings can optimize financial growth through smart strategies. Leveraging high-yield accounts and employer contributions ensures maximized returns and efficient asset allocation.
Leveraging High-Yield Savings Accounts
High-yield savings accounts offer significantly better interest rates compared to traditional savings accounts. They can earn between 0.50% to 2% APY, depending on the bank and market conditions.
To automate savings, individuals can set up regular transfers from checking to a high-yield savings account. This can be a fixed amount deposited monthly or a percentage of income. Automatic transfers ensure consistent saving without needing manual intervention.
Many institutions allow easy online setups. They may provide tools for tracking goals, making it easier to visualize progress. This visibility can encourage maintaining or increasing contributions over time.
Taking Advantage of Employer Contributions
Employers often provide matching contributions for retirement savings plans like 401(k)s. This means that for every dollar contributed by the employee, the employer adds a certain percentage, effectively providing “free” money toward retirement.
Employees should understand the terms of matching contributions, including the minimum required contributions to qualify. Automating contributions to meet these minimums ensures employees do not miss out on this valuable benefit.
Setting the contribution percentage to at least the maximum match can substantially increase retirement savings over time. Regularly reviewing this amount during salary increases can also boost savings without impacting current finances.
Automating Retirement Savings and Investments
Automating contributions to retirement accounts, such as IRAs and 401(k)s, allows individuals to save consistently for the future. By setting up automatic deductions from a paycheck or bank account, they can steadily build their retirement fund.
For IRAs, individuals can establish monthly transfers to fund their accounts. Similar to employer plans, this consistent saving can leverage compound interest effectively over the years.
Investing in a diverse portfolio can enhance growth potential. Automated investment platforms, or robo-advisors, streamline this process. They periodically review and rebalance portfolios based on set risk preferences and goals, ensuring investments stay aligned without requiring ongoing oversight.
Monitoring and Adjusting Your Savings Strategy
Regular monitoring and adjustments are crucial for maintaining an effective savings strategy. By analyzing income, expenses, and saving patterns, individuals can ensure their financial plan remains aligned with their goals and circumstances.
Regular Review and Rebalancing
Regular reviews of savings accounts and strategies should occur at least quarterly. This review process helps assess how automatic savings contributions align with current income and expenses.
During the review, it is important to check the performance of any investment accounts as well. If savings goals have been met or if the financial situation has improved, individuals may consider increasing contributions.
Additionally, creating a detailed overview of income and expenses can provide insight into patterns. A simple table can help visualize these figures:
| Category | Amount |
| Monthly Income | $3,500 |
| Fixated Expenses | $2000 |
| Variable Expenses | $800 |
| Target Saving | $700 |
Adjustments should follow this review to respond to changing financial needs.
Dealing With Changes in Income and Expenses
Life circumstances can impact income or expenses significantly. Job changes, unexpected expenses, or major life events can require a reassessment of savings plans.
When income increases, it may be advantageous to raise automatic contributions to savings accounts or investment accounts. If expenses rise unexpectedly, consider reducing discretionary spending, allowing for continued contributions to an emergency fund.
Creating a flexible budget can aid in adapting to these changes. It is crucial to:
- Identify Essential vs. Non-Essential Spending
- Allocate More Towards Savings When Possible
- Maintain a Buffer in the Emergency Fund
By actively managing these adjustments, individuals can maintain their savings momentum, securing their financial future.